

For decades, individuals have been captivated by property, often seeing buy-to-let as a guaranteed way to get rich. But is it really that simple? Managing these properties can be tough and stressful, and many who succeed do so because of luck and timing.
Buy-to-let seems appealing because it’s something you can see and touch and managing mortgage debt feels familiar. But there are hidden costs and risks. High rental yields can be misleading, and the stories of success rarely mention the stress and failures. On the other hand, other options such as investment accounts or pensions can provide significant tax advantages and the opportunity for more reliable outcomes returns when invested wisely.
Some people see buy-to-let as an alternative to low-yield savings, but it involves significant risks, especially if borrowing is involved. It’s like starting a business with all its costs and risks. Without careful planning, investors may face financial difficulties if markets go against them. Whilst property investing allows for easy leverage, this amplifies both gains and losses. Historically, UK property values have fallen significantly during downturns.
Many new investors are attracted by high monthly rents of around 6% of the property value on average1. However, the costs are substantial. Initial costs include stamp duty and repairs, while ongoing costs cover insurance, maintenance, and potential vacancy periods. Investors are advised to budget 30% to 35% of gross income for these costs2. Any remaining income is taxed, with some small tax breaks available. Sale costs include agent fees and capital gains tax.
When you crunch the numbers, the after-cost return of buy-to-let investments is often much lower than headlines might imply, which makes property price increases crucial for buy-to-let success. Comparing a more reasonable 2% after-cost rental return on buy-to-let with traditional portfolios shows that traditional investments, even with a 1% annual cost, have been more reliable.
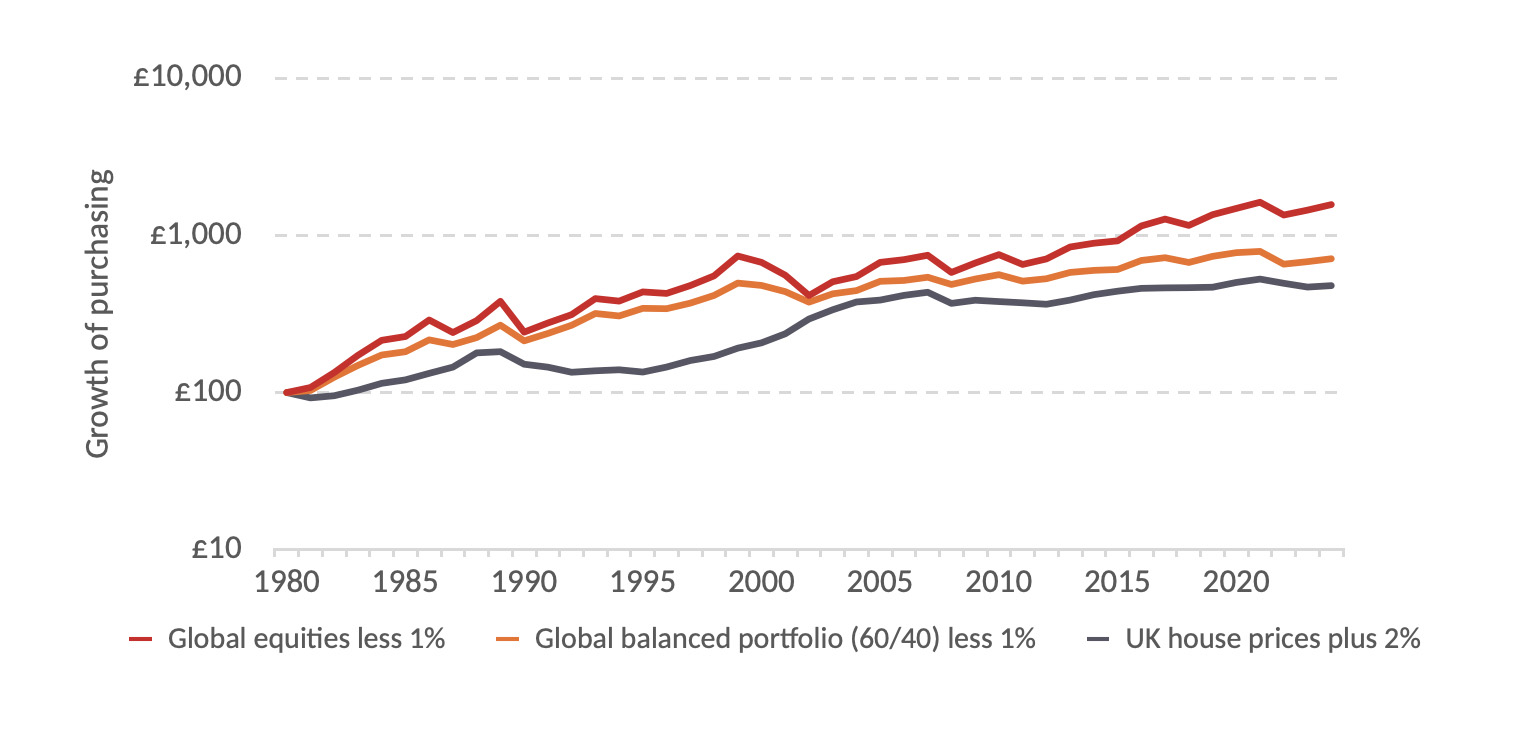
Figure 1: Buy-to-let versus traditional portfolios – simulated strategies after inflation 1981-2024
Data source: See endnote 3
In the end, it’s important to look at the bigger picture and make informed decisions. Whether it’s a buy-to-let or investing in stocks and bonds, understanding the risks and benefits will help you make the best choice for your financial future.
- ONS © Private rent and house prices, UK: April 2025.
- Before it was merged with other financial bodies in 2017, the Council of Mortgage Lenders (CML) advised holding back 30-35% of rental income to service ongoing costs.
- Global equities Albion World Stock Market Index (AWSMI). Balanced (60/40) = 60% ‘Global equities’, 40% Albion 2.5Y UK Constant Maturity Bond Index. Costs of 1% have been deducted from the ‘traditional’ portfolios and portfolios were rebalanced back to the original mix once a year. UK house prices = Nationwide House Price Index.
Benefit from comprehensive, integrated, and objective advice.
Let’s discuss your specific needs and how I can help you meet your objectives
Let’s start the conversation
Online enquiry form
Related posts
 Published On: October 5, 2026|4.9 min read|
Inheritance Tax: The Six-Month Deadline Families Often Overlook
Inheritance tax is usually due within six months, often before the house can be sold. How executors can pay it when the wealth is tied up in property.
Read more
 Published On: September 28, 2026|7.6 min read|
Your Pensions Don’t Know You Have Other Pensions
Most people collect several pensions over a working life, but none of them know the others exist. Why that's a collection of pots, not a retirement plan.
Read more
 Published On: September 18, 2026|5.4 min read|
The Risk Hiding in the ‘Safe’ Part of Your Portfolio
Your pension may hold more gilts than you realise. How the bond market prices government borrowing, and why "safe" is not the same as free from risk.
Read more