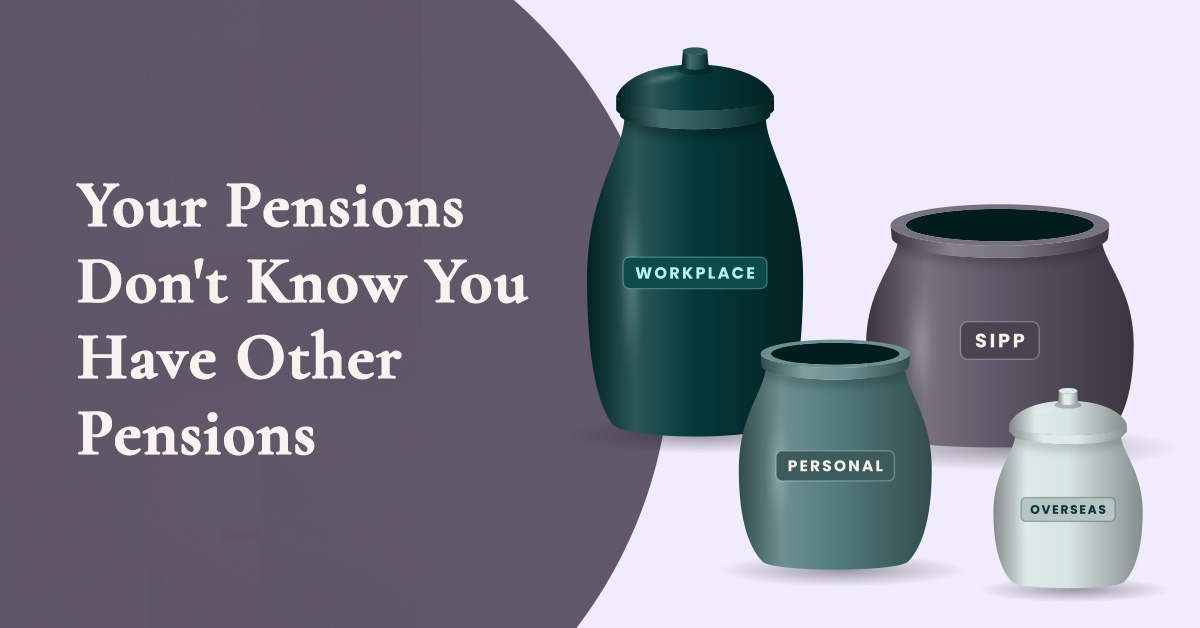
One of the stranger things about retirement planning is that we can spend 30 or 40 years building something that isn’t really a plan at all. We change jobs and a new pension gets opened. We move country and another gets left behind. An employer changes provider, we start a personal pension somewhere else, and before long there are four, five or six different pots accumulated over a working lifetime.
The odd thing is that none of these pensions knows the others exist. The pension you started in your thirties doesn’t know about the one you joined in your forties. Your old workplace scheme doesn’t know how much cash you have, your SIPP doesn’t know you have a final salary pension coming at 65, and none of them knows when you actually want to stop working or how much you expect to spend when you do.
Yet somehow this collection of accounts is supposed to fund one retirement.
When I look at someone’s pensions for the first time, I’m usually much less interested in how many they have than whether anybody has ever looked at them together. Quite often, nobody has.
The accidental portfolio
Most people don’t deliberately build a portfolio of pensions. They accumulate one, usually as a by-product of changing jobs and getting on with their lives.
You might have £80,000 in one pension invested cautiously, £150,000 in another sitting in a default fund and £300,000 in a SIPP invested much more aggressively. Taken individually, there may be nothing obviously wrong with any of them. Put them together and you can discover that the overall investment mix bears very little resemblance to the amount of risk you thought you were taking.
There can be plenty of duplication too. Five funds with five impressive-sounding names may turn out to own many of the same companies. At the other extreme, a pension you assumed was sensibly diversified might have a surprisingly large exposure to one market, sector or type of asset.
Old retirement dates cause another problem. A workplace pension may still be working towards the retirement age you entered when you joined the scheme 20 years ago. Some funds gradually change their investments as that date approaches, often moving away from equities and towards bonds and cash. If you have since decided to work for another five years, retire ten years earlier or draw from a completely different pension first, the fund has no way of knowing.
You can therefore end up with investments being rearranged automatically because of a date you barely remember choosing.
Tidying up can be an expensive mistake
The obvious solution is to consolidate everything. Sometimes that is exactly the right thing to do. One provider, one valuation and one investment strategy can make life considerably simpler, and it becomes much harder to forget that a pension exists when you can see everything together.
But I wouldn’t transfer an old pension simply because it makes the filing cabinet neater.
Some older pensions contain benefits that are difficult or impossible to replace. Guaranteed annuity rates, protected tax-free cash, protected pension ages and other valuable terms can be buried inside policies that otherwise look thoroughly unremarkable. Transfer the pension and those benefits may disappear with it.
Before deciding where anything should go, I want to know what is already there. What does it cost? How is it invested? Are there guarantees? Are there exit penalties? What retirement options does it offer? Is there anything valuable that would be surrendered on transfer?
Only after answering those questions does consolidation become a sensible conversation.
£800,000 doesn’t tell me whether you can retire
Suppose you have £800,000 spread across four pensions. It’s tempting to focus immediately on the investments: which provider is cheapest, which fund has performed best or whether everything should be moved onto one platform.
None of that answers the question most people actually want answered, which is whether they have enough to retire.
An £800,000 pension can be more than enough for one person and nowhere near enough for another. Retiring at 55 is very different from retiring at 67. Spending £3,000 a month bears little resemblance to spending £8,000. A mortgage disappearing at 60 changes the calculation, as does a State Pension, a defined benefit pension, rental income, an inheritance or a partner who intends to carry on working.
I would much rather start with the life the money is expected to fund and work backwards.
What will you actually spend? When do you want to stop working? Which expenses disappear and which might increase? What other income will arrive later? How much flexibility do you have if markets have a dreadful year?
Once you know those things, the individual pensions begin to make much more sense because you can decide what role each of them should play.
Retirement spending doesn’t arrive neatly each month
One of the assumptions I dislike about retirement planning is that somebody retires at 60, chooses an annual income and then spends exactly that amount, increased neatly with inflation, for the rest of their life.
Real people aren’t quite so cooperative.
The first decade of retirement can be expensive. There may be more travel, a new car, work on the house, children to help and, most importantly, more free time in which to spend money. Later, expenditure may fall. State Pensions start, defined benefit pensions come into payment and other sources of income can appear at different ages.
That makes the order in which you use your money important.
Cash, ISAs, pensions and other investments don’t have to be drawn in equal proportions every year. Nor does every pension need to be invested identically. Money likely to be needed in the next few years has a very different job from money that may remain invested for another 20.
This becomes particularly important when markets fall. The problem isn’t simply seeing the value of a pension go down; it’s having to sell investments after they have fallen because that is where next month’s spending has to come from. A retirement plan should allow for bad markets rather than assuming they will politely avoid the years in which you need money.
Don’t leave the detective work to somebody else
There is another reason old pensions deserve some attention now.
From April 2027, most unused pension funds and death benefits are due to be brought into the inheritance tax calculation. Pensions that many families have spent years regarding as separate from the estate will therefore become much more relevant to estate planning.
That makes beneficiary nominations worth checking too. People marry, divorce, have children, move countries and lose touch with people who once seemed permanent. An expression of wish completed 15 or 20 years ago doesn’t know any of that has happened.
If you have several pensions, you may also have several different nominations made at completely different stages of your life. The person eventually dealing with your affairs first has to know that all those pensions exist before they can begin dealing with them.
I spend a fair amount of my working life tracking down information from pension providers, and even with letters of authority, reference numbers and professional support, it isn’t always quick. I would rather not leave that detective work to somebody who is also dealing with everything else that follows a death.
Give every pension a reason to be there
I don’t think everybody needs to end up with one pension. There are perfectly good reasons to retain more than one, particularly where an older scheme contains valuable benefits or different pensions are being used for different purposes.
What I do think is that every pension should have a reason for being where it is.
An old scheme might stay untouched because it contains a valuable guarantee. Another might be transferred because its charges are high, its investment choice is poor or it no longer fits the wider plan. One part of the portfolio might eventually provide spending in the earlier years of retirement while money intended for much later can remain invested for growth.
If your pensions are scattered across previous employers and providers, don’t begin by deciding where to transfer them. Start by finding out exactly what you have. Record the values, charges and investments, check the retirement ages, look for guarantees or protected benefits and make sure the beneficiary nominations still reflect what you actually want.
Then forget about the pensions for a moment and think about the retirement.
When would you like work to become optional? What would you like to spend? What income will arrive from elsewhere? What large expenses are likely to come along? What do you want to leave behind, if anything?
Once those questions have answers, you can come back to the pensions and decide what each one is there to do.
Four pensions aren’t necessarily a problem. But if nobody has ever stood back and looked at what all four are trying to achieve together, there is a reasonable chance you have accumulated a collection of pension policies rather than a retirement plan.
Benefit from comprehensive, integrated, and objective advice.
Let’s discuss your specific needs and how I can help you meet your objectives
Let’s start the conversation
Online enquiry form
Related posts
 Published On: October 5, 2026|4.9 min read|
Inheritance Tax: The Six-Month Deadline Families Often Overlook
Inheritance tax is usually due within six months, often before the house can be sold. How executors can pay it when the wealth is tied up in property.
Read more
 Published On: September 18, 2026|5.4 min read|
The Risk Hiding in the ‘Safe’ Part of Your Portfolio
Your pension may hold more gilts than you realise. How the bond market prices government borrowing, and why "safe" is not the same as free from risk.
Read more
 Published On: September 11, 2026|7.9 min read|
Six Funds. One Portfolio. More Overlap Than You Think.
This is one of the things you notice when you spend enough time looking through investment portfolios. People often own the same companies far more times than they realise. It doesn't make those companies bad investments. It does mean the number of funds in your portfolio tells you almost nothing about how diversified you really are.
Read more